What a mortgage valuation actually is
A mortgage valuation is commissioned by your lender, paid for (usually) by you, and carried out to answer exactly one question: is this property worth what the lender is being asked to lend against it? It is typically a brief visit — sometimes only a drive-by or a desktop assessment using comparable sales data — and the resulting report is often only a handful of lines long.
Crucially, the valuer's duty of care runs to the lender, not to you. You may never even see the full report, and if it does flag a condition issue, it will usually be phrased as a condition of lending (“subject to a damp specialist's report”) rather than as advice to you about whether to proceed with the purchase.
Typical time spent on a drive-by or desktop mortgage valuation
Who the valuer's duty of care is owed to — your lender, not you
Condition ratings, defect narrative, or repair advice included as standard
The real differences, side by side
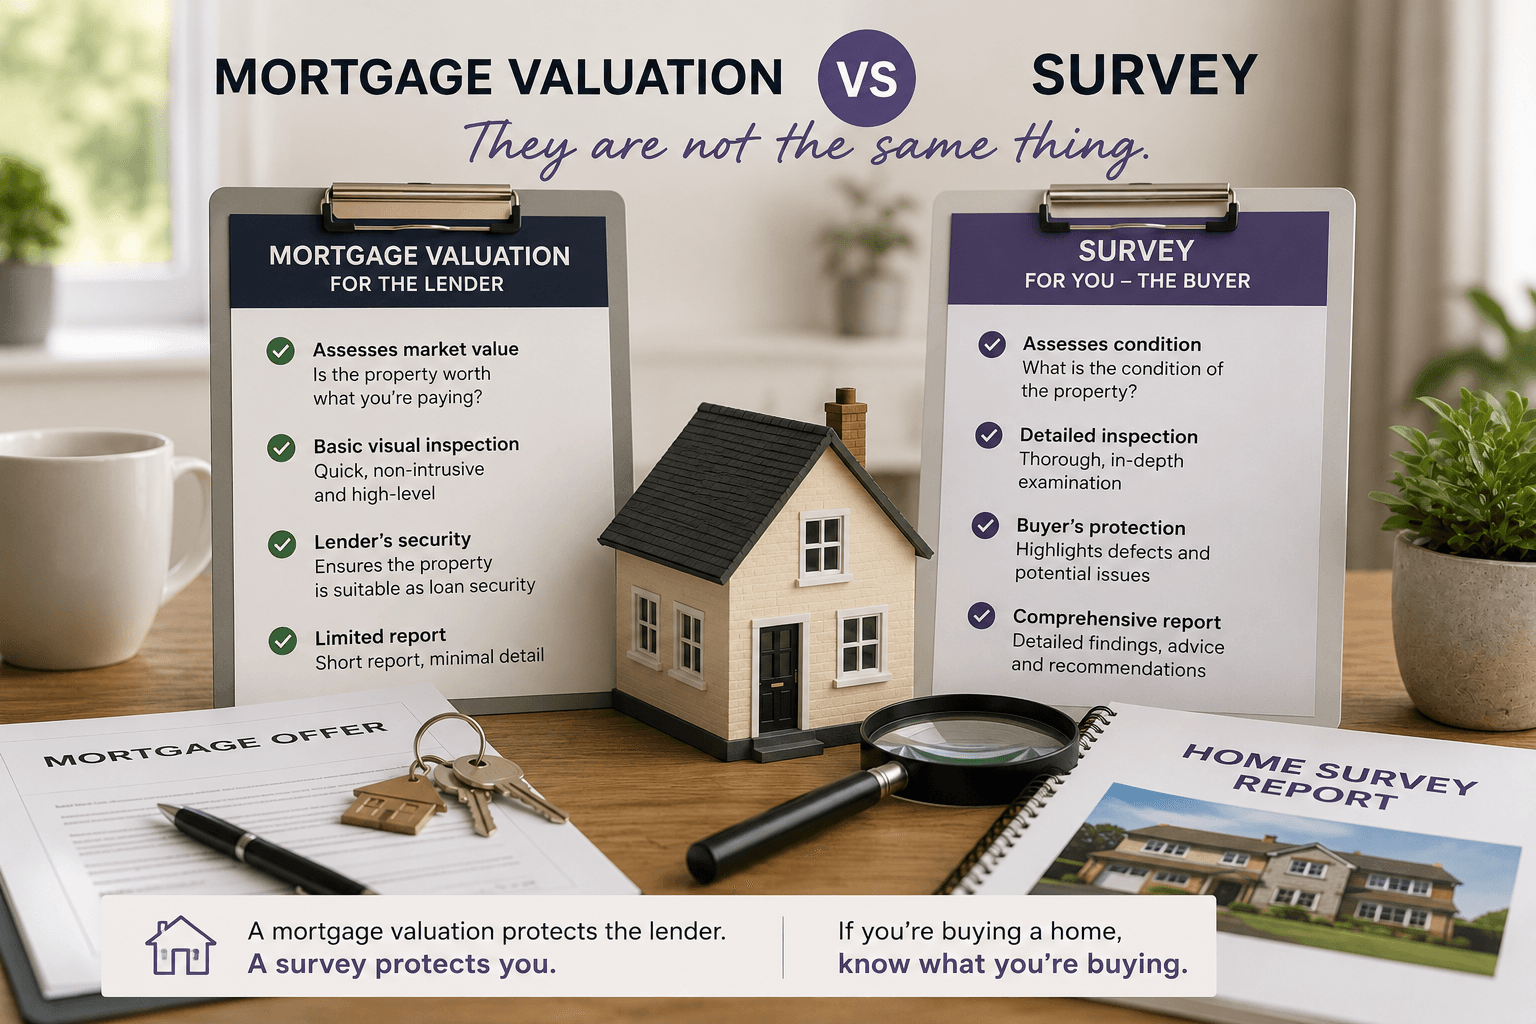
Who it's for. Mortgage valuation: your lender. RICS survey: you, the buyer, commissioned specifically for your protection.
What it inspects. Mortgage valuation: a brief external and sometimes internal look, focused on value. Survey: a detailed inspection of accessible parts of the whole property, focused on condition.
What you get. Mortgage valuation: a short lender-facing report, often not shared with you in full. Survey: a full written report with condition ratings, photographs, and a follow-up call.
Duty of care. Mortgage valuation: owed to the lender. Survey: owed to you.
A mortgage valuation will typically tell you
- • Whether the property supports the lending amount requested
- • Occasionally, that a specialist report is required before funds release
- • Very little about the day-to-day condition of the property
A mortgage valuation will not tell you
- • Whether the roof, damp-proofing or drainage need repair
- • What's causing any defect it happens to notice
- • What a repair is likely to cost, or how urgent it is
- • Anything at all if you're a cash buyer with no mortgage involved
“The mortgage valuation is not a survey. It is a five-line desktop check for the lender, and every year we see buyers treat it as though it were both.”
Why lenders don't require more than this
Lenders are only exposed to the loan-to-value ratio, not the full value of the property, so their risk is already partially protected by your deposit. That is why their valuation can afford to be brief — the lender's downside is capped. Yours isn't. If the property needs £15,000 of roof repairs, that cost sits entirely with you, whether or not the mortgage valuation happened to notice the roof at all.
Cash buyers feel this gap most acutely, because there's no mortgage valuation at all in the process, brief or otherwise — nothing stands between you and the property's actual condition except a survey you choose to commission yourself.
Don't rely on your lender's valuation alone
Book a RICS survey commissioned for you, with a written report and a call to talk through the findings.
Get a quoteMortgage valuation vs survey: FAQs
The bottom line
Your lender's valuation protects your lender. Your survey protects you. They are not substitutes, they are not the same length, and they are not looking for the same things. Budget for both, and don't let the first one arrive and lull you into skipping the second.
A step-by-step walkthrough for first-time buyers: what to book, when to book it, how to read the report, and how to renegotiate on defects.
A practical decision guide to choosing between a RICS Home Survey Level 2, a Level 3 Building Survey or a valuation — by construction, type and condition.